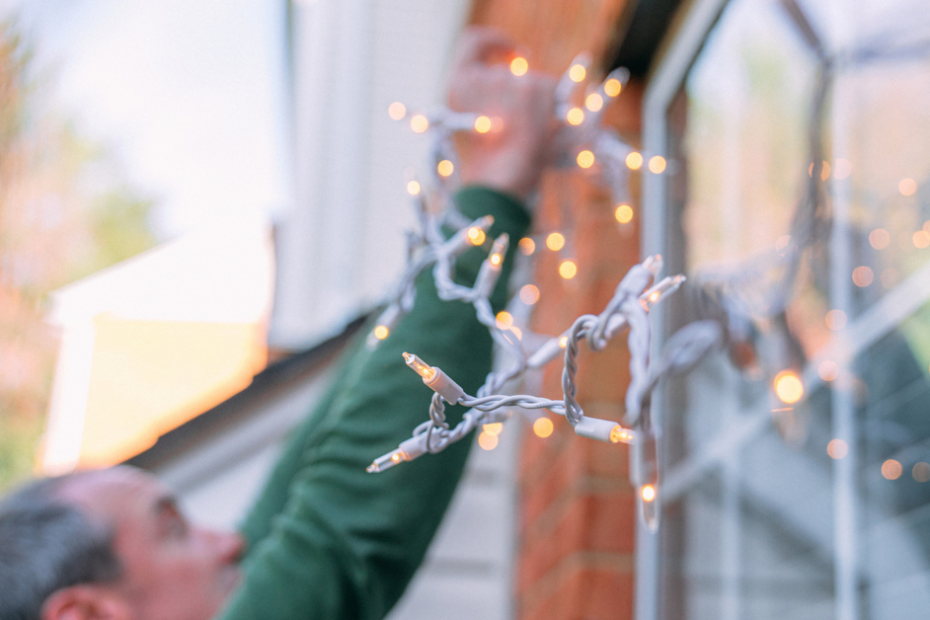
You step outside to find your inflatable pumpkin slashed, a string of lights ripped down, or your favorite lawn display simply gone. It’s an annoying way to start the day, and it raises a fair question: can homeowners insurance help with any of this, or are you on your own? The short answer is that homeowners insurance may often cover holiday decorations, but “often” comes with some real conditions worth understanding before you assume a claim is the right move.
Does Homeowners Insurance Cover Holiday Decorations?
Your holiday decorations are considered personal property, and personal property coverage is a standard part of most homeowners policies. According to Mercury Insurance, this part of your policy covers your belongings, including things like furniture, electronics, and appliances, if they’re damaged, destroyed, or stolen due to a covered event, and that protection typically follows your property even outside the walls of your home.
That matters for decorations specifically, since so many of them live in your yard rather than inside your house. Theft and vandalism of outdoor decorations, lawn displays, and lights are generally treated the same as any other personal property loss, covered under a standard policy up to your policy’s limits, whether the item is sitting in your living room or out on your lawn.
What Part of My Policy Actually Pays for This?
This falls under Coverage C, or personal property coverage, rather than your liability or dwelling coverage. It’s a good distinction to know, since it means the payout depends on your personal property coverage limit and deductible, not on who was at fault or whether anyone was hurt.
It’s also worth knowing that personal property coverage generally responds to specific causes of loss, like theft, vandalism, or fire, rather than covering anything that happens to an item. So a pumpkin that gets smashed is a different scenario, coverage-wise, than a decoration that deteriorates over time on its own. If a display is more of a built/semi-permanent structure rather than something you set out and take down each season, it’s worth asking your agent whether it falls under personal property or under your other structures coverage instead.
When Does It Make Sense to File a Claim for Holiday Decorations?
Just because something is technically covered doesn’t always mean filing a claim is the right call. You’ll pay your deductible before any reimbursement kicks in, so if your stolen or damaged decorations cost less than that deductible, there’s nothing left for the insurer to pay. A $150 broken inflatable against a $1,000 deductible, for example, simply doesn’t clear the bar.
There’s also the payout method to consider. Personal property claims are typically paid at actual cash value unless you’ve added replacement cost coverage, which means your payout accounts for depreciation. A five-year-old light display, for example, wouldn’t be reimbursed at what it costs to replace today, but at what it was worth given its age and condition, which can shrink the payout more than people expect.
A few situations worth weighing before you file a claim for holiday decorations:
- The loss is close to or under your deductible: You’d be paying for the claim yourself anyway, so there’s little reason to file.
- You’ve filed other claims recently: Mercury notes that claims can affect your future rates, so a small decoration loss may not be worth the risk to your premium.
- The items were older or already showing wear: Since payouts are typically based on actual cash value, older decorations may only bring back a fraction of what they cost new.
- You can’t document what was lost: Insurers generally want proof of ownership, like receipts or photos, and a police report is often expected for theft or vandalism claims.
What About Expensive Lighting or Effects Systems?
If your holiday decoration display has grown into something elaborate, such as custom lighting controllers, animatronics, or a large-scale synchronized light show, it’s worth checking whether your standard personal property limit is enough to even replace it. Standard coverage is built to handle everyday belongings, and unique or high-value items can be underinsured relative to what they’d actually cost to rebuild.
This is where scheduled personal property coverage comes in. Mercury describes it as an endorsement that provides higher, itemized coverage for specialty or valuable belongings that go beyond what a standard policy is designed to reimburse. Common examples leans toward jewelry, antiques, artwork, and collectibles, but the coverage isn’t limited to those categories. If you’ve invested serious money into a custom holiday display, it’s worth asking your agent whether scheduling that equipment, or at least documenting it with receipts and photos, makes sense for your situation.
Talk to an AIS Insurance Specialist
Whether it’s a stolen inflatable or a light show you’ve spent years building, it’s worth knowing where your coverage actually stands before something happens to it. AIS can help you understand what your personal property coverage includes, how your deductible would factor into a claim, and whether a scheduled endorsement makes sense for anything particularly valuable. Call (888) 772-4247 or start a quote online to review your options.
The information in this article is obtained from various sources and offered for educational purposes only. It should not replace the advice of a qualified professional. The definitions, terms, and coverage in a given policy may be different than those suggested here. No warranty or appropriateness for a specific purpose is expressed or implied.